
Canned Tuna Market Size Set to Reach $21.18 Billion by 2031 Driven by Clean-Label Demand and Marine Stewardship Certification – Mordor Intelligence
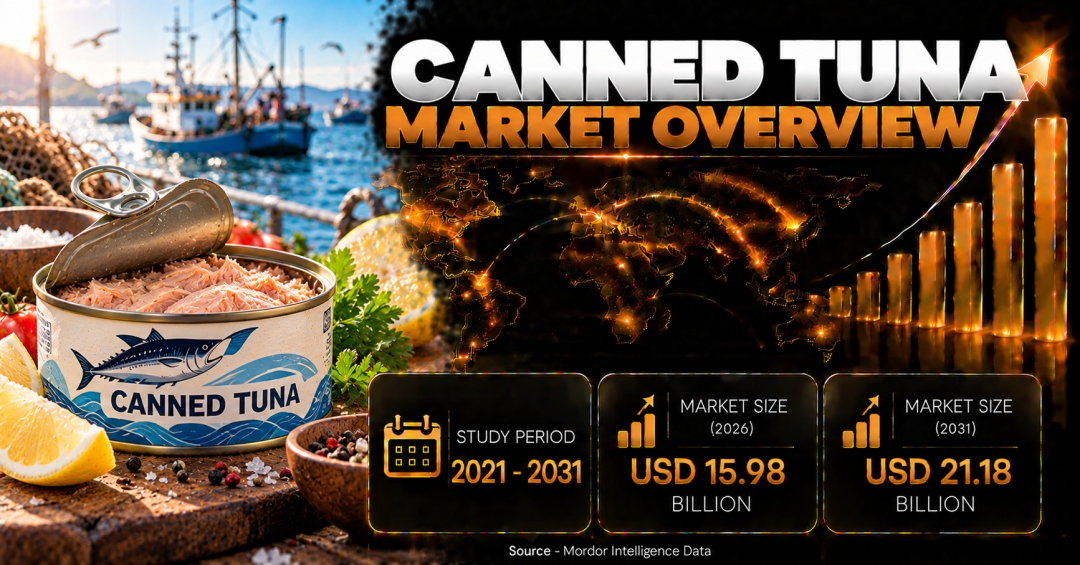
Hyderabad, October 15, 2026: According to Mordor Intelligence, the canned tuna market size is projected to be $15.98 billion in 2026 and reach $21.18 billion by 2031, growing at a CAGR of 5.80% during the forecast period (2026-2031). The market continues to expand as price-sensitive households, active fitness consumers, and commercial foodservice operators prioritize convenient, shelf-stable marine protein that fits daily culinary requirements. Rising consumer awareness regarding omega-3 fatty acids, continuous post-pandemic volume recovery across food service channels, and expanding retail availability of convenient seafood products continue to support demand across supermarket, discount grocery, and digital commerce channels worldwide.
The canned tuna market growth is also influenced by changing international seafood sustainability standards and evolving consumer expectations regarding ethical harvest traceability and metal packaging reduction. Seafood processors are investing in flexible retort pouches, pole-and-line catching partnerships, and Marine Stewardship Council (MSC) certified supply chains. These operational developments are helping businesses respond to stricter governmental dietary guidelines and environmental benchmarks while maintaining sensory quality, moisture retention, and product shelf life. Together, these factors continue to strengthen the integrated canned tuna market forecast across mature and emerging seafood markets.
Canned Tuna Market Trends
Light Tuna Maintains Volume Leadership Driven by Food Safety Guidelines
One of the leading canned tuna market trends is the sustained consumer preference for light tuna varieties, primarily sourced from skipjack tuna. Skipjack carries significantly lower mercury accumulation compared to larger pelagic species, aligning with health and safety agency guidance such as the United States Food and Drug Administration’s ‘Best Choice’ dietary recommendations for pregnant women and children. This nutritional advantage, coupled with economical pricing and broad availability, ensures light tuna remains the foundational volume driver for family meal planning and school lunch nutrition. The widespread availability of skipjack continues to support the canned tuna industry.
Marine Stewardship Certification and Ethical Sourcing Accelerate Premium Tiers
While conventional canned tuna provides consistent baseline volume within the canned tuna market share, certified sustainable and artisanal white tuna products represent the fastest-growing value segment. Environmentally conscious shoppers and specialty retailers actively seek albacore and yellowfin tuna harvested through pole-and-line, troll-caught, or Fish Aggregating Device (FAD)-free methods that minimize marine bycatch. Seafood brands are highlighting full vessel-to-can traceability and MSC blue checkmarks on retail labels, aligning with broader manufacturing standards seen across the integrated food ingredients industry for sustainable seafood supply chains.
Flexible Pouches and Single-Serve Formats Modernize Packaging Efficiency
Packaging format diversification remains an essential area of development across the canned tuna market growth. While standard metal cans continue to dominate bulk pantry storage due to high barrier protection and long shelf life, flexible retort pouches and glass jars are recording rapid retail adoption. Pouches eliminate the need for can openers and draining, reducing steel consumption and shipping weight while offering seasoned, ready-to-eat tuna salads for on-the-go snacking. These convenient format adaptations help seafood processors attract younger urban consumers seeking quick, high-protein meal additions.
E-Commerce Subscriptions and Direct-to-Consumer Multipacks Broaden Retail Access
Distribution channels continue to play a significant role in market deployment. Off-trade grocery channels account for the largest share of retail revenue through hypermarkets and supermarket shelves. Concurrently, digital commerce platforms are recording the fastest climb through curated multipack bundles and recurring subscription deliveries. Online storefronts enable direct-to-consumer seafood brands to communicate their ethical fishing narratives directly to shoppers while securing repeat orders for specialty gourmet lines and infused flavored varieties.
Europe Retains Volume Leadership While Middle East and Africa Lead Growth Rate
Regional consumption dynamics continue to influence the canned tuna market forecast. Europe commands the largest regional market share, supported by traditional Mediterranean dietary habits in Spain, Italy, and France, mature canned seafood markets, and extensive private-label distribution networks. Meanwhile, the Middle East and Africa region represents the fastest-growing market, propelled by rapid urbanization, rising disposable incomes, and state-backed investments in localized canning infrastructure to reduce import dependency, such as large-scale industrial canning plants in Oman. Evolving consumer food habits continue to create new opportunities for producers expanding their regional presence.
Check out more details and stay updated with the latest industry trends, including the Japanese version for localized insights: https://www.mordorintelligence.com/ja/industry-reports/canned-tuna-market?utm_source=abnewswire
Canned Tuna Market Segmentation
By Product Type
- White Tuna (Albacore)
- Light Tuna (Skipjack and Yellowfin)
By Flavor
- Flavored
- Unflavored
By Packaging Type
- Metal Cans
- Pouches
- Glass Jars
By Distribution Channel
- On-Trade (Foodservice)
- Off-Trade (Retail)
By Geography
- North America
- Europe
- Asia-Pacific
- South America
- Middle East and Africa
Competitive Landscape of the Canned Tuna Industry
The canned tuna industry exhibits a moderate level of market concentration, with multinational seafood conglomerates, vertically integrated fleet operators, and regional private-label packers competing across fleet access, canning automation, and retail distribution agreements. Market leaders are strengthening their market presence by securing long-term supply agreements with certified fishing cooperatives, modernizing high-speed retort processing facilities, and expanding value-added flavored lines to protect margins against volatile skipjack commodity price swings.
Sourcing traceability, dolphin-safe certification, and cold-chain integrity continue to be critical areas of differentiation as processors invest in satellite vessel tracking and automated quality sorting to ensure consistent cut grading. Businesses are also refining distribution partnerships with national supermarket grocers, foodservice wholesalers, and major online marketplaces to secure prime shelf visibility. These initiatives are helping companies protect their canned tuna market share while maintaining quality consistency across global distribution networks.
Regional expansion also remains an important business strategy. Leading canned tuna processors continue to build strategic commercial alliances with regional distributor networks, establish localized processing facilities in proximity to major fishing zones, and introduce region-specific spice marinades to capture growing demand across both mature and high-growth markets. As global commercial demand for convenient, nutrient-dense seafood continues to rise, the canned tuna market forecast remains supported by ongoing investments in responsible marine harvesting, automated packaging systems, and international brand expansion.
Key Players
Major companies operating in the canned tuna market include:
- Thai Union Group PCL
- Dongwon Group
- Bolton Group
- Bumble Bee Foods
- Century Pacific Group, Inc.
Conclusion
The canned tuna market forecast remains positive as consumers and foodservice operators worldwide continue prioritizing affordable, shelf-stable proteins that deliver clean nutrition, long storage life, and culinary versatility. Seafood processors and brand owners are responding by expanding certified pole-and-line offerings, improving pouch barrier technologies, and developing gourmet marinades that cater to changing consumer tastes. These developments are expected to support continued demand across multiple commercial foodservice and domestic retail channels.
Strategic regulatory alignment and marine resource stewardship are becoming increasingly vital as businesses adapt to stricter fishery conservation quotas and evolving consumer expectations regarding packaging sustainability. At the same time, specialized single-serve convenience pouches and expanded direct-to-consumer digital subscription models are helping companies enhance overall product appeal while supporting long-term commercial goals. These structural developments continue to guide modern canned tuna market trends.
Regional opportunities also remain strong. Europe provides a dependable, high-volume commercial baseline, while the Middle East and Africa offer attractive growth pathways as localized canning infrastructure and urbanization accelerate canned seafood adoption. This shift is expected to create new commercial avenues for canned tuna processors expanding their operational footprint in developing markets.
Overall, the canned tuna market size is expected to benefit from changing consumer dietary habits, growing demand for affordable protein alternatives, wider availability across digital and brick-and-mortar retail channels, and an ongoing commitment to sustainable fishery management. Together, these factors are expected to support sustained canned tuna market growth while strengthening the long-term outlook for the global canned tuna industry.
Industry Trending Reports
Meat Extract Market: The global meat extract market is projected to reach USD 7.72 billion by 2031, expanding at an 8.49% CAGR from its 2026 valuation of USD 5.14 billion. Category momentum is driven by commercial food processors incorporating concentrated animal-protein matrices into shelf-stable bouillons, prepared soups, and culinary seasoning blends. Food manufacturers are consolidating procurement around certified suppliers that provide verifiable species authenticity, stringent microbiological standards, and consistent dissolved solids content for industrial batch processing.
Freeze Dried Food Market Size: The global freeze-dried food market is estimated at USD 39.38 billion in 2026 and is forecast to climb to USD 57.94 billion by 2031, registering an 8.03% CAGR. Demand expansion is anchored by emergency pantry stocking, outdoor recreation, and rapid adoption of freeze-dried raw formulations across premium pet food segments. Industrial processors are transitioning from legacy batch sublimation systems to automated continuous sublimation lines, lowering baseline utility overhead while preserving cell structure, rehydration capacity, and heat-sensitive micronutrients.
Frozen Food Market Share: The global frozen food market is valued at USD 326.83 billion in 2026 and is projected to expand to USD 414.55 billion by 2031, growing at a 4.87% CAGR. Market expansion is driven by consumer demand for shelf-stable meal convenience, alongside widespread adoption of Individual Quick Freezing (IQF) technology to safeguard texture, moisture retention, and nutritional profiles. In parallel, public and private capital allocations into temperature-controlled cold chains across emerging regions are minimizing inventory spoilage and expanding retail and e-commerce distribution networks.
About Mordor Intelligence:
Mordor Intelligence is a global market intelligence firm, founded in 2014, helping businesses make informed decisions through data-driven insights, industry expertise, and advanced analytics. With 550+ domain experts and on-ground specialists across 150+ countries, the company delivers comprehensive intelligence across aerospace & defense, agriculture, automation, automotive, chemicals & materials, consumer goods & services, electronics, energy & power, financial services, food & beverages, healthcare, hospitality & tourism, information & communications technology, and logistics.
Its offerings include syndicated industry reports, custom research and advisory, and subscription platforms such as Synapse, Data Center Intelligence, and Robotics Intelligence. Mordor Intelligence is ISO 9001:2015 and ISO/IEC 27001:2022 certified, a member of ESOMAR and the Market Research Society of India, and a four-time Great Place to Work® honoree.
Media Contact
Company Name: Mordor Intelligence
Contact Person: Jignesh Thakkar
Email: Send Email
Phone: +1 617-765-2493
Address:11th Floor, Rajapushpa Summit, Nanakramguda Rd, Financial District, Gachibowli [email protected]
City: Hyderabad
State: Telangana 500008
Country: India
Website: https://www.mordorintelligence.com/industry-reports/canned-tuna-market?utm_source=abnewswire


